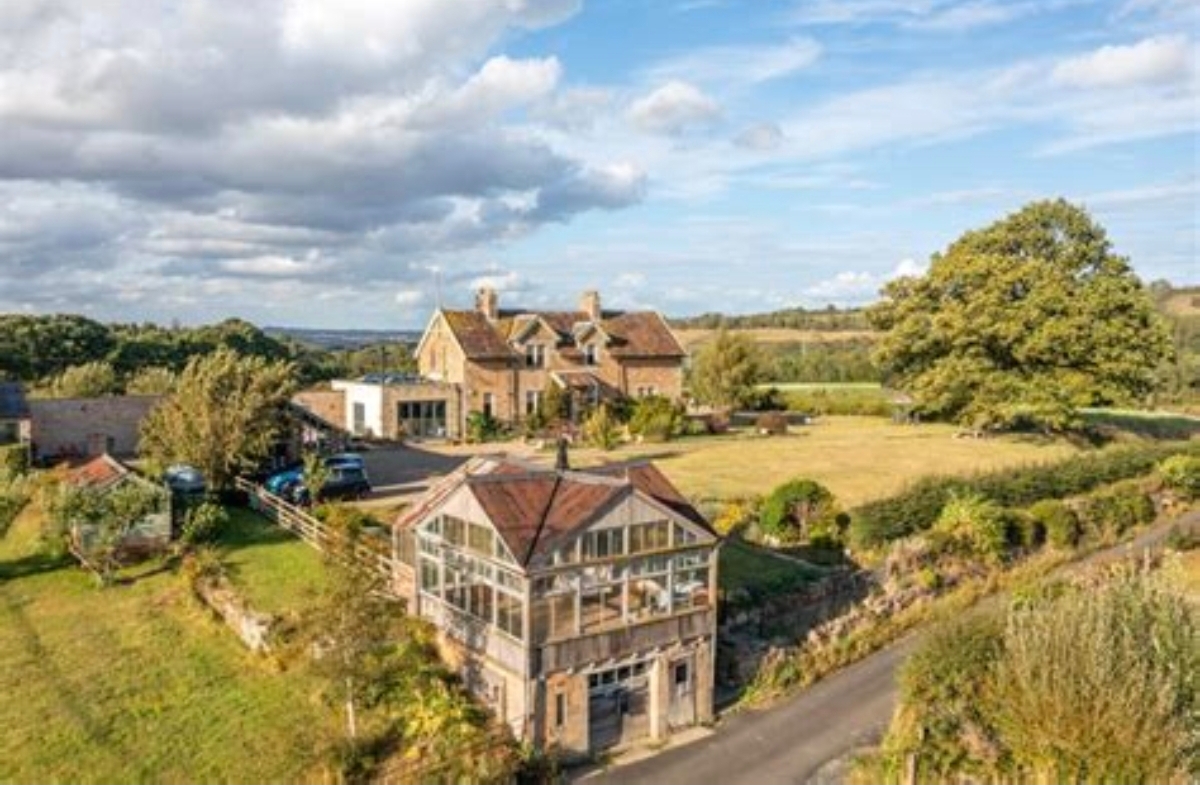
Stocksfield, Northumberland
Wheelbirks Estate
Guide price £6.75m
Estate, separate assets, rural operating business, or a platform for a new destination?
- 386.39 acres / 156.37 hectares
- Approximately 271 acres farmland
- Approximately 110 acres woodland
- Residences, commercial and hospitality infrastructure
Snowball insight
One address. Multiple assets, businesses, obligations and futures.
Wheelbirks is not one asset. The opportunity combines land, homes, agricultural and woodland interests, commercial occupation, visitor infrastructure, an operating-company history and a recognised destination brand.
The central diligence question is whether a buyer is acquiring a £6.75m estate, separate assets, a rural operating business, or a platform for a new rural destination.
The Wheelbirks Parlour reportedly closed on 6 September 2026. Historical trading success must not be represented as a currently operating business. A rapid transition workstream is required to preserve knowledge, relationships and optionality.
The acquisition question
Estate, separate assets, rural operating business, or a platform for a new destination?
The £6.75m question
The guide price cannot be understood responsibly until the transaction perimeter is separated.
Residential
Homes, cottages, occupation and condition
Agriculture
Land, farming agreements and stewardship
Woodland
Timber, ecology and long-term management
Commercial
Leases, buildings and rent roll
Visitor infrastructure
The Parlour, parking, customer facilities and restart needs
Corporate
Company, charges, contracts and liabilities
Brand & IP
Name, domains, data, goodwill and transfer rights
Equipment
Owned, leased, financed, optional and excluded items
Employees
Current position, TUPE, knowledge and transition
Tax & VAT
Structure, SDLT, TOGC, options and allowances
Opportunity
Alternative use and rural ecosystem potential
Residential + land + woodland + commercial + transferable business/IP - liabilities - transaction friction = component hypothesis
Time-sensitive transition
The Wheelbirks Parlour reportedly closed on 6 September 2026
Historical destination success and a currently trading operation are different facts. Secure closure reasons, management accounts, employee and supplier knowledge, licences, customer channels, equipment ownership and brand rights before optionality decays.
Historical
Destination profile and prior customer activity require evidenced accounts.
Current
Closed. No current trading income is assumed.
Future
Restart, operator lease, repositioning or repurpose remain concepts to validate.
Restart-cost explorer
Editable provision to frame evidence requests, not a forecast.
Illustrative restart provision
£725,000
Editable placeholder only. It excludes acquisition price, tax, professional fees, finance and unknown liabilities.
Estate and business income map
Treat each income centre as a separate business before consolidating the estate case.
| Operating centre | Possible current basis | Evidence required |
|---|---|---|
| Homes | Existing residential income | Tenancy schedule, arrears, EPC and condition |
| Agriculture | Farm income and support arrangements | Occupancy, cropping, costs and scheme transfer |
| Woodland | Forestry and stewardship | Inventory, permissions and management obligations |
| Commercial | Leases and occupational income | Executed leases, reviews, breaks and repairing terms |
| Destination | Historical Parlour activity | Closure pack, accounts, operator and restart scope |
| Future platform | New complementary enterprises | Demand, planning, capex and partner evidence |
Asset and occupation register
Assets are deliberately separated so occupation, income, value and strategy are never blended.
Principal estate residence
LowResidential
- Current occupancy
- To verify
- Tenancy
- Unknown
- Current rent
- Unknown
- Estimated market rent
- Not assessed
- Indicative vacant-possession value
- Professional valuation required
- Condition
- Survey required
- EPC
- Unknown
Potential strategies
- Retain
- Let
- Destination anchor
Estate cottages and residential interests
LowResidential
- Current occupancy
- Mixed / to verify
- Tenancy
- Schedule required
- Current rent
- Unknown
- Estimated market rent
- Not assessed
- Indicative vacant-possession value
- Professional valuation required
- Condition
- Survey required
- EPC
- Unknown
Potential strategies
- Hold
- Re-let
- Selective disposal
Farmland
MediumAgricultural
- Current occupancy
- Mixed occupation to verify
- Tenancy
- Agricultural agreements required
- Current rent
- Unknown
- Estimated market rent
- Not assessed
- Indicative vacant-possession value
- Not a formal valuation
- Condition
- Land capability review required
- EPC
- Not applicable
Potential strategies
- Direct farming
- Contract farming
- Letting
- Regenerative transition
Woodland compartments
LowWoodland
- Current occupancy
- Estate controlled / to verify
- Tenancy
- Unknown
- Current rent
- Unknown
- Estimated market rent
- Unknown
- Indicative vacant-possession value
- Standing timber is not cash
- Condition
- Inventory and management plan required
- EPC
- Not applicable
Potential strategies
- Forestry
- Natural capital
- Recreation
- Conservation
Wheelbirks Parlour visitor infrastructure
MediumCommercial
- Current occupancy
- Recently closed
- Tenancy
- Operational perimeter unknown
- Current rent
- Not currently evidenced
- Estimated market rent
- Operator assessment required
- Indicative vacant-possession value
- Component valuation required
- Condition
- Reopening survey required
- EPC
- Unknown
Potential strategies
- Restart
- Lease to operator
- Reposition
- Repurpose
Farm and commercial buildings
LowInfrastructure
- Current occupancy
- Mixed / to verify
- Tenancy
- Lease schedule required
- Current rent
- Unknown
- Estimated market rent
- Unknown
- Indicative vacant-possession value
- Survey and valuation required
- Condition
- Asbestos and condition surveys required
- EPC
- Unknown
Potential strategies
- Agricultural use
- Rural workspace
- Light industrial
- Storage
Wheelbirks brand and digital assets
LowHeritage
- Current occupancy
- Ownership unverified
- Tenancy
- Not applicable
- Current rent
- Unknown
- Estimated market rent
- Not assessed
- Indicative vacant-possession value
- IP valuation only if transferable
- Condition
- Rights audit required
- EPC
- Not applicable
Potential strategies
- Transfer
- Licence
- New identity
Interactive estate and occupation map
Click a marker and switch analysis layers. All boundaries remain unverified.
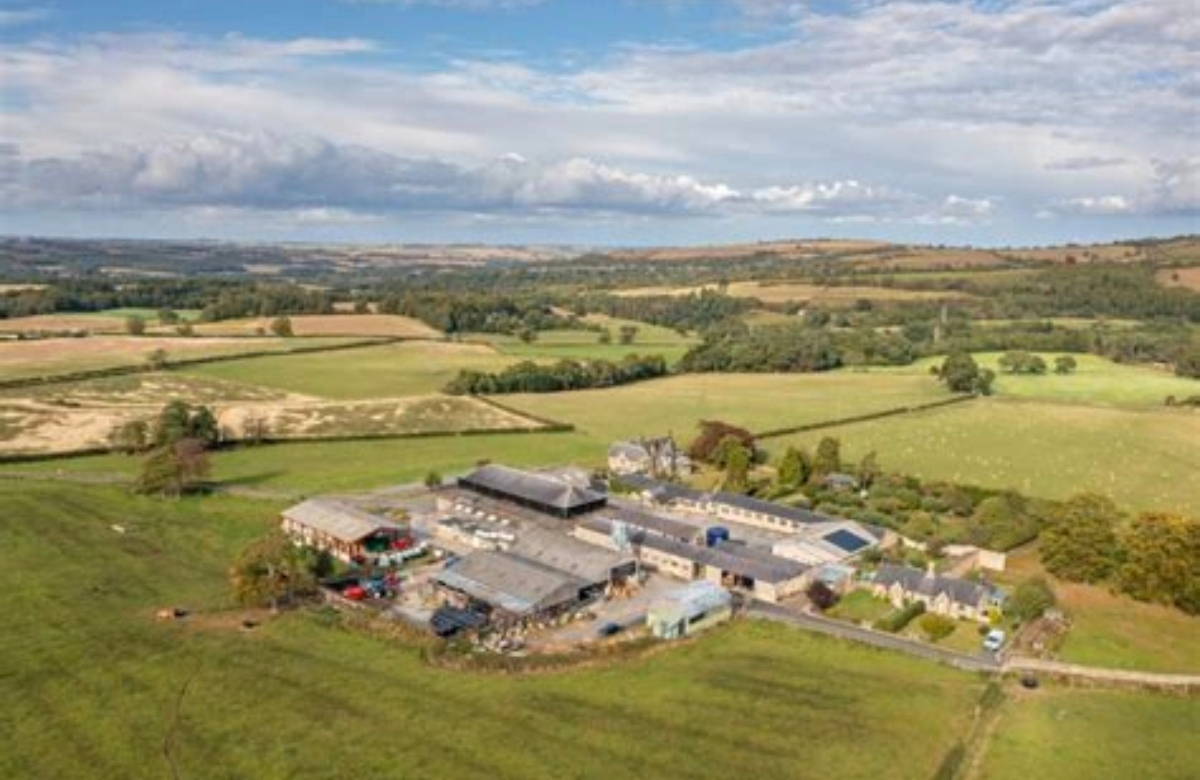
Indicative analytical image and markers only. This is not a title plan, measured survey or verified boundary map.
Selected area
Farmland
- Area
- Approximately 271 acres
- Current use
- Agriculture and environmental stewardship
- Restrictions
- Tenure, cropping and scheme terms unknown
- Income
- Farm accounts not supplied
- Next action
- Reconcile parcels, occupation and schemes
Land, agriculture and woodland
Productive land needs an operating thesis, not just an acreage figure.
Compare direct farming, contract farming, letting and regenerative transition. Verify SFI or Countryside Stewardship agreements, payment basis, obligations, control and transfer. For woodland, establish compartments, species, age, access, disease, felling licences, replanting duties, safety and management cost before modelling timber or natural capital.
Agriculture
Direct, contract, let or regenerative
Stewardship
Do not assume scheme payments transfer
Woodland
Standing timber is not cash
Natural capital
Avoid double counting carbon, BNG and stewardship
Infrastructure, rights and building risks
These constraints can affect control, value, finance, operations and future use.
Pipelines
UnknownRoute and easement plans required
Overhead electricity
UnknownWayleave, capacity and safety constraints to verify
Public and private rights of way
UnknownMap routes, maintenance and interference risk
Wood Cottage access
UnknownConfirm benefitting land, route, maintenance and rights
Water, drainage and utilities
UnknownCapacity and ownership information required
Farm-building condition
UnknownCondition, asbestos and compliance surveys required
Asset purchase versus share purchase
The Wheelbirks Estate Company Limited is reported active, company number 00761642, incorporated in 1963. Obtain current filings and professional advice.
Asset purchase
- Define each title, asset, contract, IP right and liability transferring.
- Potentially clearer liability perimeter, but continuity and transfer work may be extensive.
- Model SDLT, VAT, capital allowances, employees and contracts professionally.
Share purchase
- Company continuity may preserve contracts and history, subject to terms.
- Known and unknown liabilities may remain within the company.
- Six charges are reported, three outstanding. Charges are not equivalent to current debt.
Snowball analysis is not legal advice. Material legal matters should be reviewed by appropriately qualified professionals.
| Area | Issue to investigate | Assigned adviser |
|---|---|---|
| Purchase perimeter | Asset and share-purchase routes carry materially different liabilities and tax outcomes. | Corporate and property lawyers |
| Registered charges | Six charges are reported, three outstanding. A charge must not be equated with current debt; obtain instruments and redemption evidence. | Corporate lawyer and lender |
| Occupation | Residential, agricultural and commercial occupation must be mapped before assuming control or vacant possession. | Rural surveyor and solicitor |
| VAT and tax | Option to tax, TOGC, SDLT, capital allowances and business-transfer treatment need specialist advice. | Tax adviser |
Alternative-use scenario lab
Fourteen concepts are provided to provoke disciplined investigation. None implies consent or recommendation.
Concept only
Wheelbirks rural ecosystem
A phased hybrid masterplan linking land, woodland, homes, enterprise, food and destination uses.
Opportunity
- Diversifies estate income
- Can reinforce the wider rural ecosystem
Constraints
- Planning, access, utilities and capital remain unverified
- Operator capability may be required
Evidence and partners
- Title and planning review
- Demand and operating model validation
- Cost plan
- Estate owner
- Planning adviser
Phase 1
Protect and understand
- Secure transition evidence
- Confirm titles and occupations
- Stabilise buildings and relationships
Phase 2
Operate and test
- Separate business centres
- Pilot visitor and farm offers
- Validate operator demand
Phase 3
Build the ecosystem
- Select compatible uses
- Sequence capital
- Measure community and environmental outcomes
Wheelbirks rural ecosystem
A circular model where one activity can supply demand, content or resilience to another.
Land and woodland
Food, ecology, landscape and learning
Rural enterprise
Workspace, producers, services and skills
Destination
Food, stays, events, wellness and visitors
Community value
Jobs, access, education and local supply
Multi-business financial workspace
Separate each operating centre, then test the consolidated estate case and acquisition structure.
Acquisition sensitivity
- Indicative equity
- £3,375,000
- Annual interest only
- £219,375
- Illustrative interest cover
- 1.91x
Component value model
Illustrative net component total
£6,250,000
Difference to price: £-500,000
Inputs are deliberately editable placeholders. They are not valuations, forecasts or investment advice and must not be treated as evidence of market value, finance availability or saleability.
Assumption challenge
Snowball should challenge attractive shortcuts before they become assumptions.
“£6.75m / 386.39 acres = about £17,470 per acre”
This arithmetic blends homes, buildings, woodland, infrastructure, occupation, business interests and liabilities. It is not a meaningful land valuation.
“The Parlour was successful, so it can simply reopen”
Historical success does not prove a transferable or currently trading operation. Validate closure causes, assets, people, licences, working capital and restart demand.
“The woodland can support lodges”
Land availability does not imply planning, ecology, access, fire-safety, utilities or commercial feasibility.
“Buying the company preserves everything”
A share purchase may preserve contracts but also inherit liabilities. Charges are not the same as debt. Compare asset, share and mixed structures professionally.
Due-diligence dashboard
Illustrative readiness scores highlight the work required before a responsible acquisition decision.
Investment readiness score
34%
Ready
What we still need to know
4 information items outstanding
15 critical questions
The exact questions that should drive the first evidence request.
Critical transaction questions
- -What exactly is included in the £6.75m guide price?
- -Which titles comprise the stated 386.39 acres?
- -Who occupies each residence, building and parcel, and on what terms?
- -What is the complete current rent roll and arrears position?
- -What assets, equipment and stock are excluded from sale?
- -Who owns the Wheelbirks name, trademarks, domains, social accounts and customer data?
- -What caused the Parlour closure on 6 September 2026?
- -Which employees, liabilities and obligations remain after closure?
- -What environmental agreements affect the land, and can any benefits transfer?
- -What is the woodland inventory, management plan and felling or replanting position?
- -What pipelines, overhead electricity, rights of way and access constraints affect the estate?
- -What rights serve Wood Cottage and who maintains its access?
- -Is an asset purchase, share purchase or mixed transaction contemplated?
- -What do the six registered charges secure, and which three remain outstanding?
- -What VAT, SDLT, capital allowances, TOGC and option-to-tax issues require specialist advice?
Professional validation workflow
Every material claim should move from AI identified to evidence received and professional verified.
Estate acreage and title reconciliation
Reviewer: Property solicitor / land agent
Residential and commercial rent roll
Reviewer: Rural surveyor
Parlour restart feasibility
Reviewer: Hospitality operator / accountant
Company and charge analysis
Reviewer: Corporate lawyer
Woodland and natural capital
Reviewer: Forester / ecologist
Build the acquisition and operating consortium
A mixed estate needs coordinated property, business, land, operating and community capability.
Acquisition
Lead investor / family office
RequiredPatient capital able to separate property and operating risk.
Property
Rural surveyor and RICS valuer
RequiredOccupation, component value and rural asset advice.
Legal & tax
Property and corporate legal team
RequiredTitle, charges, purchase structure, VAT and liability perimeter.
Operations
Estate general manager
RequiredDay-one coordination across tenants, land, buildings and suppliers.
Hospitality
Destination operator
RequiredIndependent restart and repositioning assessment for the Parlour infrastructure.
Land
Farm operator / agronomist
In discussionCompare direct, contract, let and regenerative operating pathways.
Woodland
Forester and ecologist
RequiredInventory, safety, management, permissions and natural-capital evidence.
Community
Local enterprise and community partner
RequiredShape jobs, access, food, learning and local value outcomes.
Source freshness and transition timeline
Chronology matters where business status and source documents can change quickly.
Sale particulars and initial opportunity mapping
Parlour closure update: 6 September 2026
Protect knowledge, staff and supplier evidence
Reconcile title, occupation and corporate perimeter
Professional validation and acquisition decision
Phased operating pilots and masterplan
Data room and professional evidence
Structure evidence by access level and preserve a visible audit trail.
Public vs private information
Public
Headline opportunity / Images / Approximate location / General opportunity / Selected future-use concepts
Registered investor
Financial modelling / Deeper asset data / Assumptions / Consortium requirements
Approved investor / adviser
Detailed diligence / Rent rolls / Leases / Title information / Confidential documents
Project team
Full data room
Document ingestion
The opportunity owner can upload source documents. Snowball extracts facts and keeps a link back to the source so every claim stays auditable, for example Source: Sales brochure - page 12.
Every extracted fact carries a source, a date, a confidence level and a known / assumed / unknown status.
Final positioning
Wheelbirks may be more valuable as a coordinated rural ecosystem than as one undifferentiated estate.
That thesis is provisional. The responsible next step is to define the assets, occupations, rights, business perimeter, liabilities, operating centres and evidence before selecting an acquisition structure or future-use pathway.